From prototype to production: where your costs go
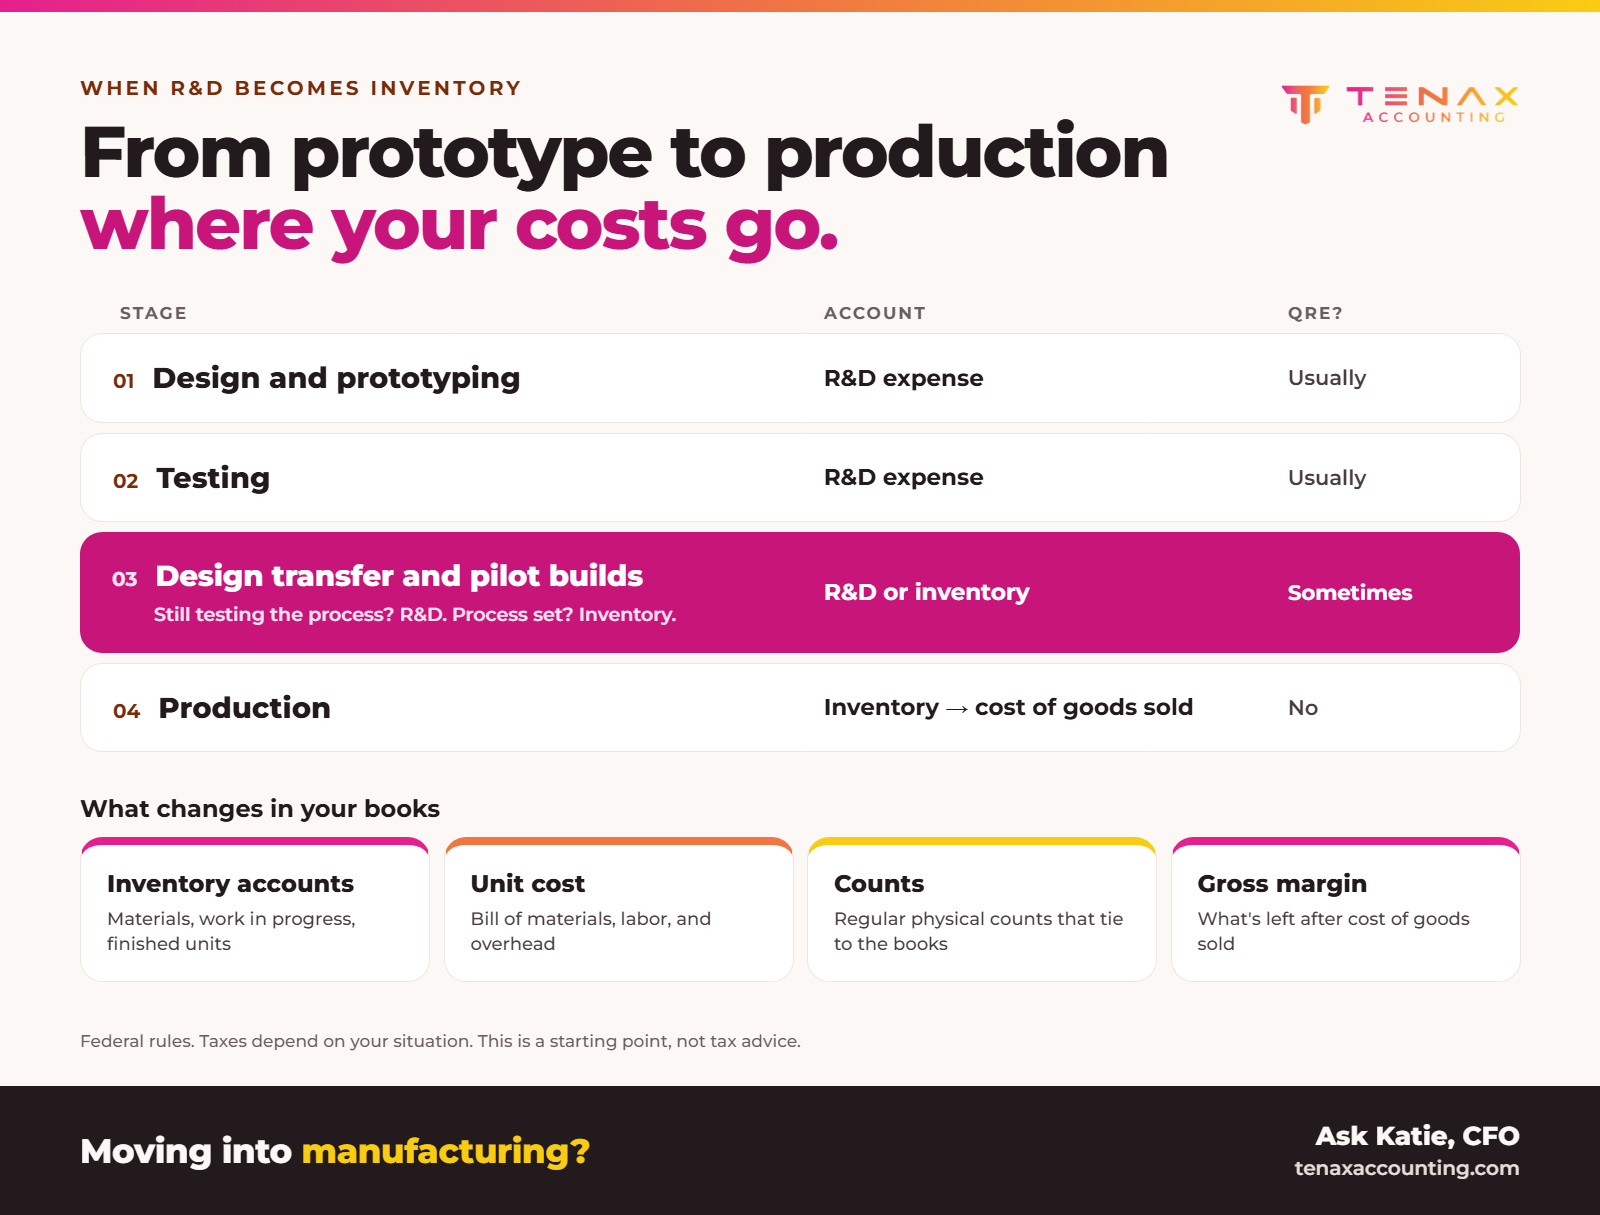
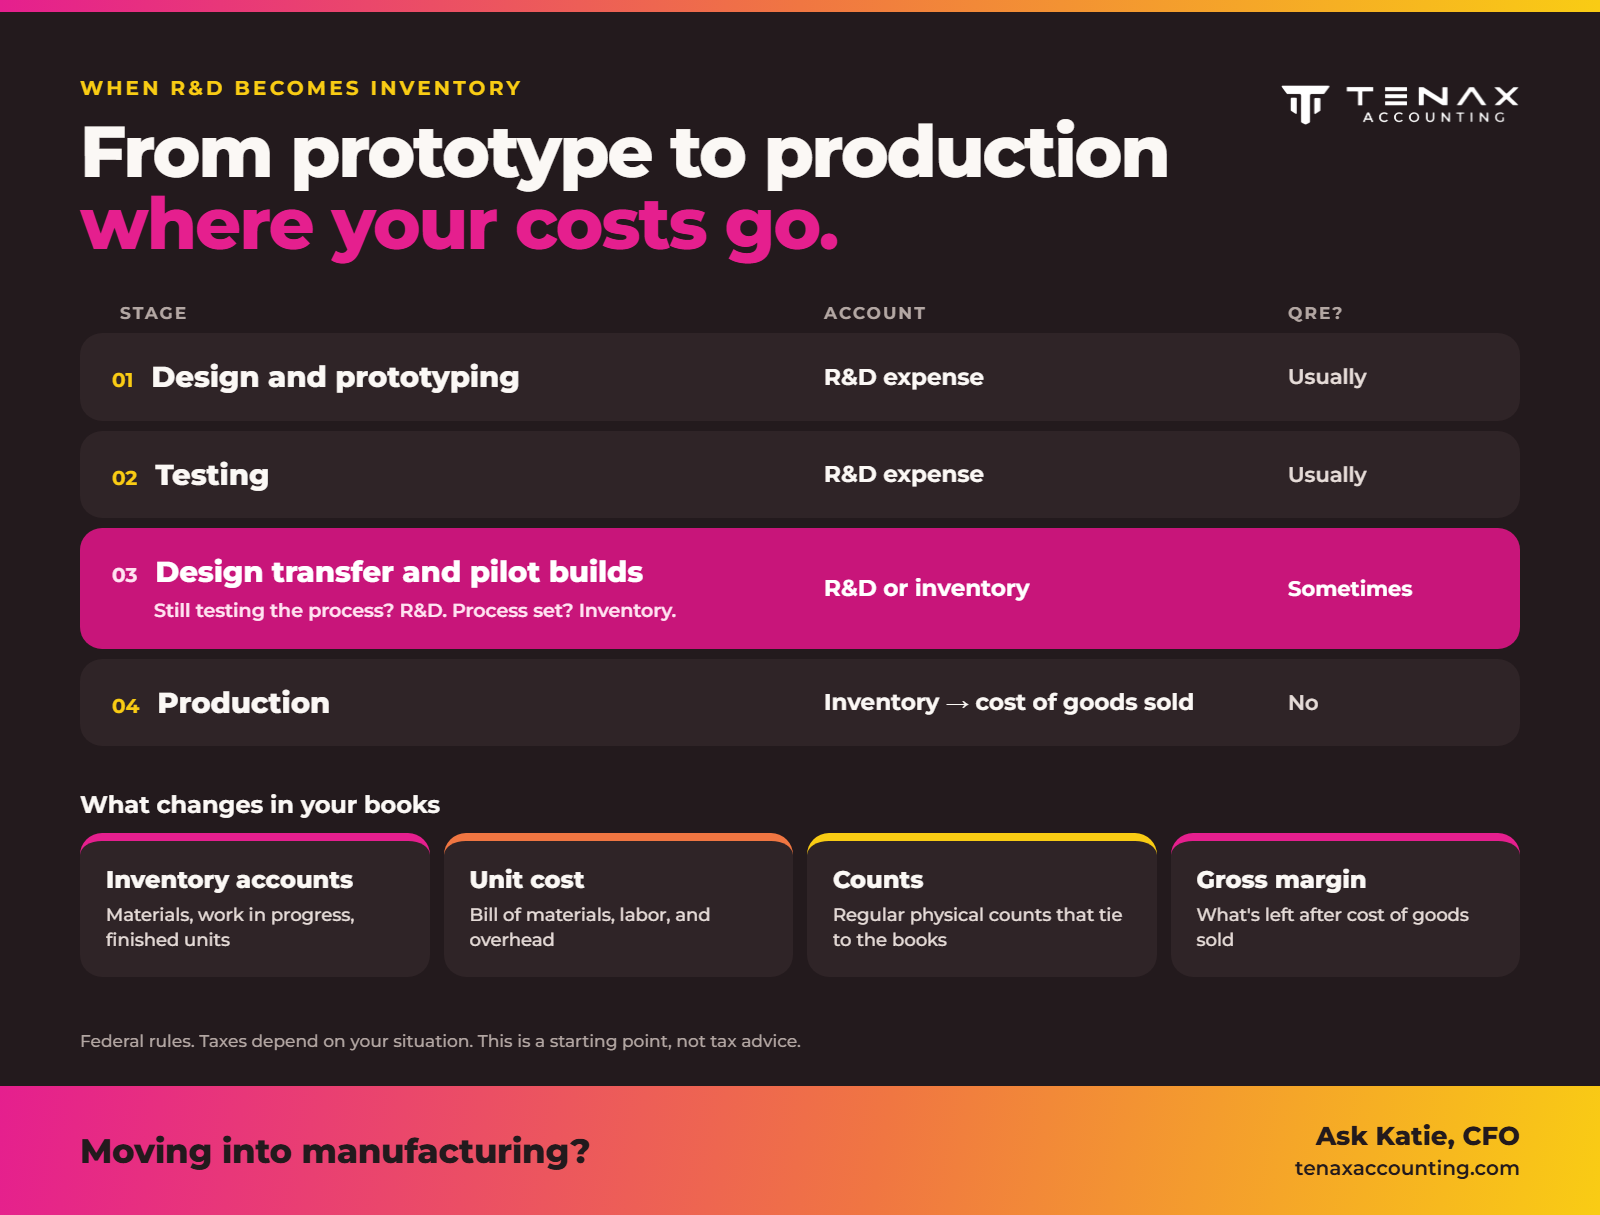
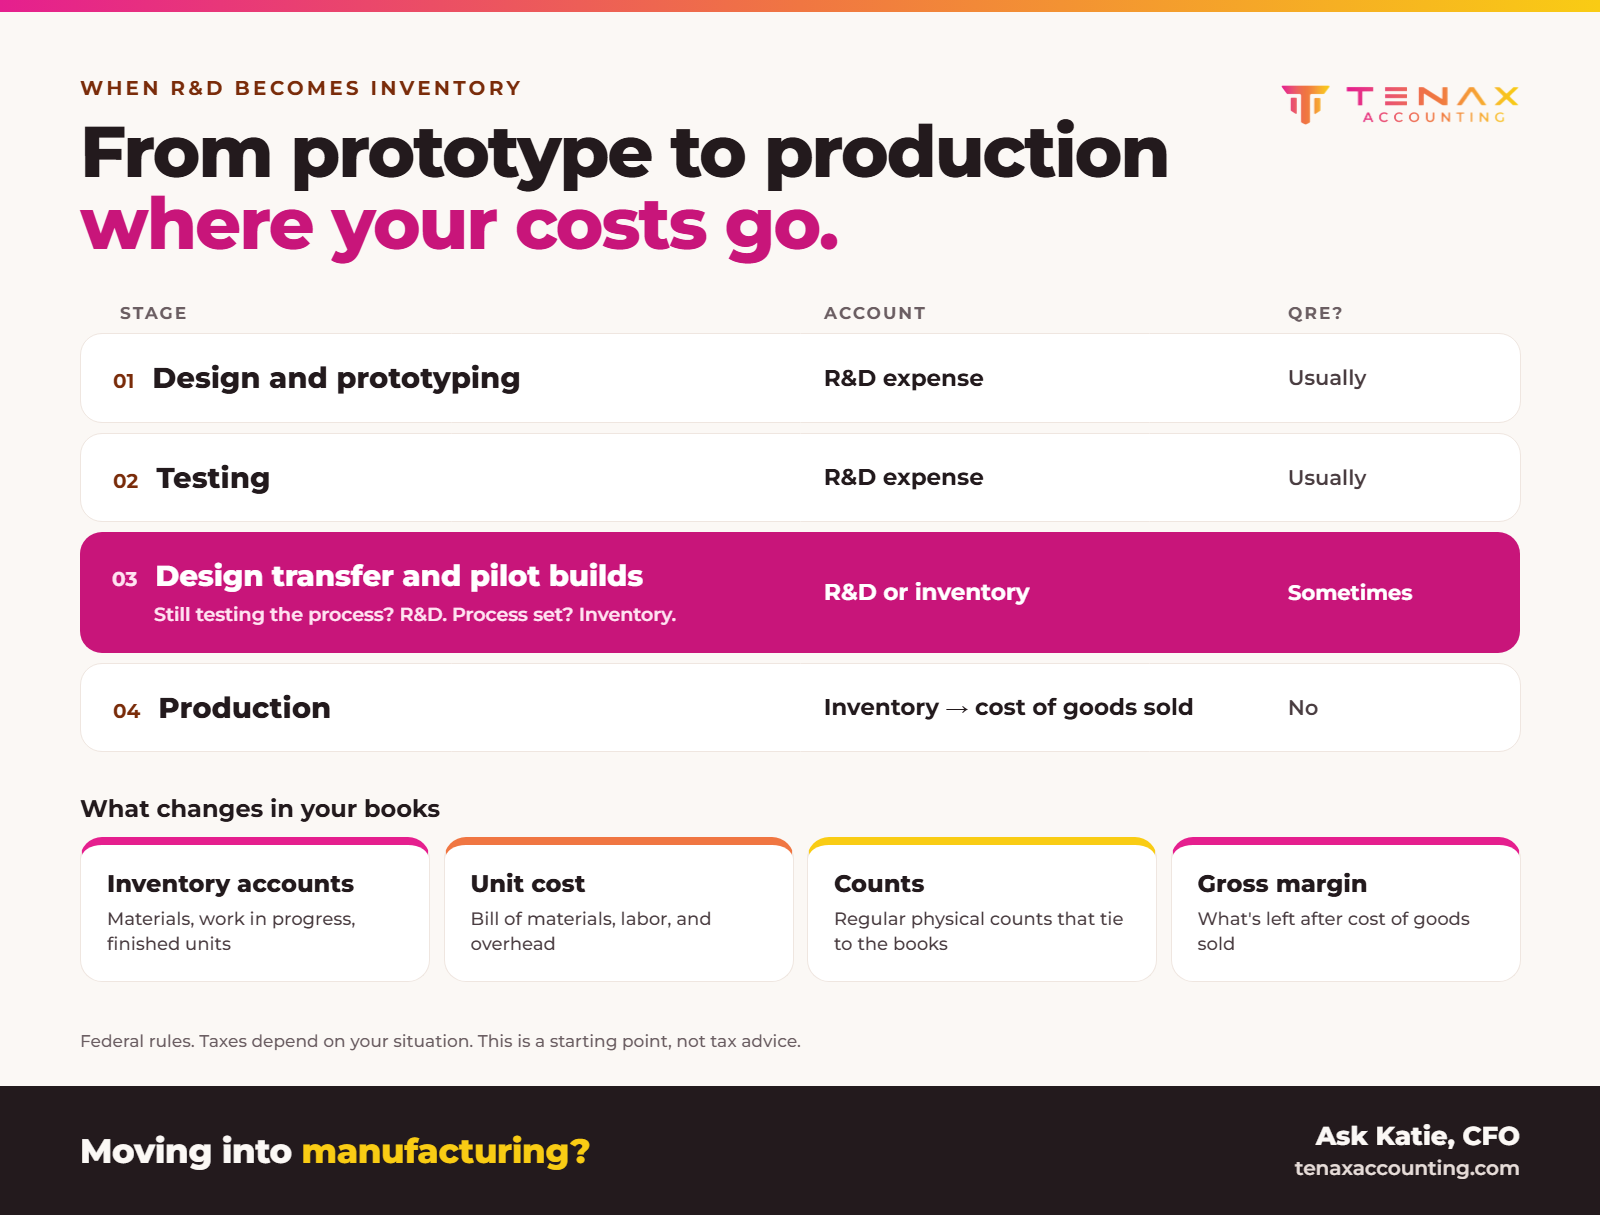
As a device moves from development into manufacturing, costs move from R&D expense to inventory, then to cost of goods sold. Here's where they go at each stage.
The short version
Design and prototyping: R&D expense, usually QREs.
Testing: R&D expense, usually QREs.
Design transfer and pilot builds: R&D while you're still testing the process, and inventory once the process is set.
Production: inventory, then cost of goods sold as units sell. Not QREs.
What changes in your books: inventory accounts, unit cost, regular physical counts, and gross margin.
Questions
When do R&D costs become inventory?+
When the manufacturing process is set and you're building units to sell. From that point, materials, labor, and overhead for those units go to inventory, and become cost of goods sold as the units sell.
Are pilot builds R&D or inventory?+
It depends on why you're building them. If you're still testing whether and how the process works, the costs are usually R&D. If the process is set and the units will be sold, they're inventory. Decide the rule before the first pilot build.
Do production costs count toward the R&D credit?+
No. Work after commercial production begins doesn't qualify. Development on a next version or a new product can still count.
Less stress.
More advantage.
Ask Katie, CFO →
15 free minutes. Real answers. No pitch.